For incorporated Canadian business owners with $150,000 in retained earnings
Take Money Out of Your Corp Without Losing Half to the Taxman
For incorporated business owners with $150,000 or more inside their corporation who are tired of being taxed every time they touch their money.
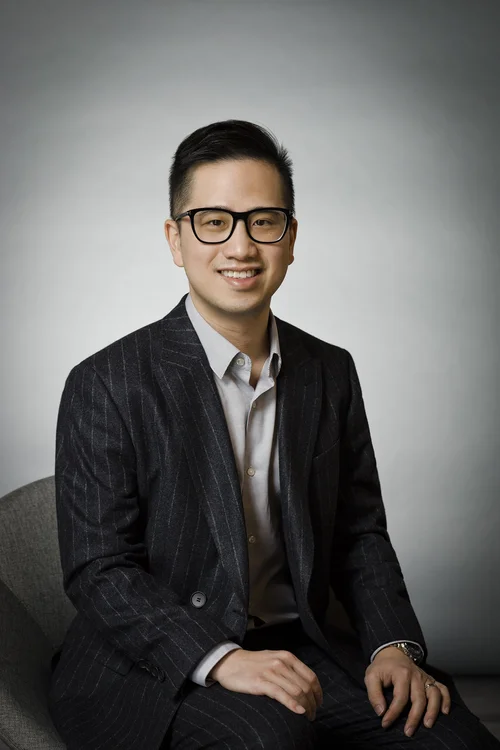
Your answers are reviewed by Andy Tsai, CFP®, CLU®, TEP and Allan Zhang, CPA, CGA, CFP®.
Case studies
Client situations are described in general terms with identifying details removed. Outcomes depend on individual circumstances and are not a guarantee of future results.
-
The Incorporated Business Owner
$1.2M annual corporate income · $300K annual retained earnings
The problem
The business owner was accumulating $300K in corporate profits annually but faced personal tax of nearly 50% when withdrawing the funds for retirement.
Our approach
Implemented a corporate-owned life insurance strategy to build wealth within the corporation while creating future access to funds.
The outcome
Created a tax-efficient alternative to personal withdrawals, helping preserve more corporate wealth for retirement and future generations.
-
The Corporation with Significant Investments
$3M in investment assets · $200K annual investment income
The problem
Significant passive investment income eliminated the corporation's small business tax deduction, resulting in higher corporate taxes.
Our approach
Restructured the investment strategy by moving the portfolio into a tax-exempt life insurance structure and reorganizing the remaining investments.
The outcome
Restored access to the small business tax deduction while creating tax-sheltered investment growth and improving overall after-tax returns.
-
The Business Owner Preparing for a $5M Exit
$5M business valuation · Third-party sale
The problem
The anticipated sale of the business could result in approximately $1.25M in capital gains taxes, significantly reducing the owner's proceeds.
Our approach
Worked with tax professionals to restructure share ownership and maximize the available lifetime capital gains exemptions across generations.
The outcome
Positioned the shareholders to utilize available lifetime capital gains exemptions, with the objective of preserving the full $5M in sale proceeds from capital gains tax.
-
The $30M Family Estate
$30M family net worth · Multiple corporations and investment portfolios
The problem
The family wanted to transfer significant wealth to the next generation while managing future tax liabilities and preserving their family legacy.
Our approach
Worked alongside specialized CPAs and lawyers to implement an estate freeze, family trust, and long-term wealth transfer strategy.
The outcome
Established a tax-efficient wealth transfer structure, locked in the value of the existing estate for tax planning purposes, and created a clear roadmap for the next generation.
Who is H2
Integrated financial planning — corporate insurance, retirement, trust and estate planning, coordinated with your professional advisors.
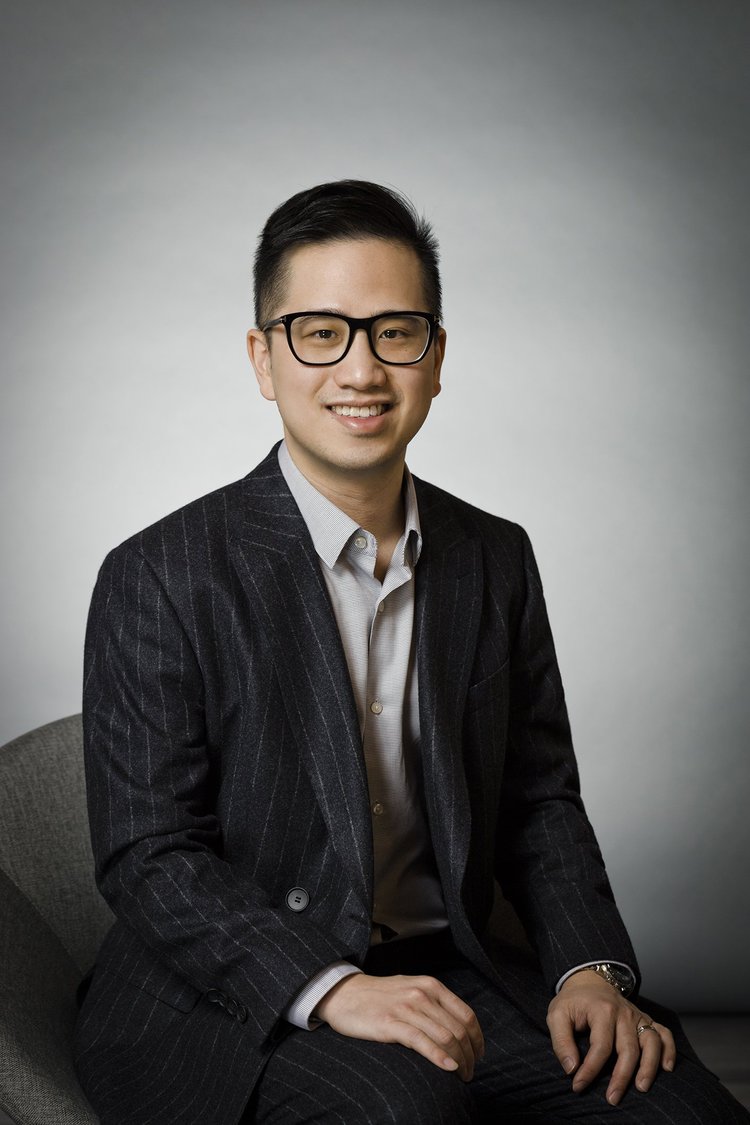
Andy Tsai CFP®, CLU®, TEP
Founder & Principal
Andy's financial planning practice focuses on complex situations where insurance, corporate structures, taxation, retirement, and estate objectives intersect. He helps clients understand how these pieces fit together and develop clear, practical solutions for the decisions ahead.
Honesty and Humility
The firm was founded on two principles that still guide how it works. Honesty — providing advice with clarity and transparency, even when the right answer is not the most obvious one. Humility — recognizing that good planning starts with listening, asking the right questions, and understanding what matters most to each client.
The team
-
Andy Tsai CFP®, CLU®, TEP
Founder & Principal · Corporate insurance and estate planning
-
Allan Zhang CPA, CGA, CFP®
Financial planning and tax · 20+ years in tax practice
-
Charlene Liu CFP®, CEA, MBA
Financial planning and insurance · 10+ years
We coordinate with your accountant and lawyer rather than replacing them.